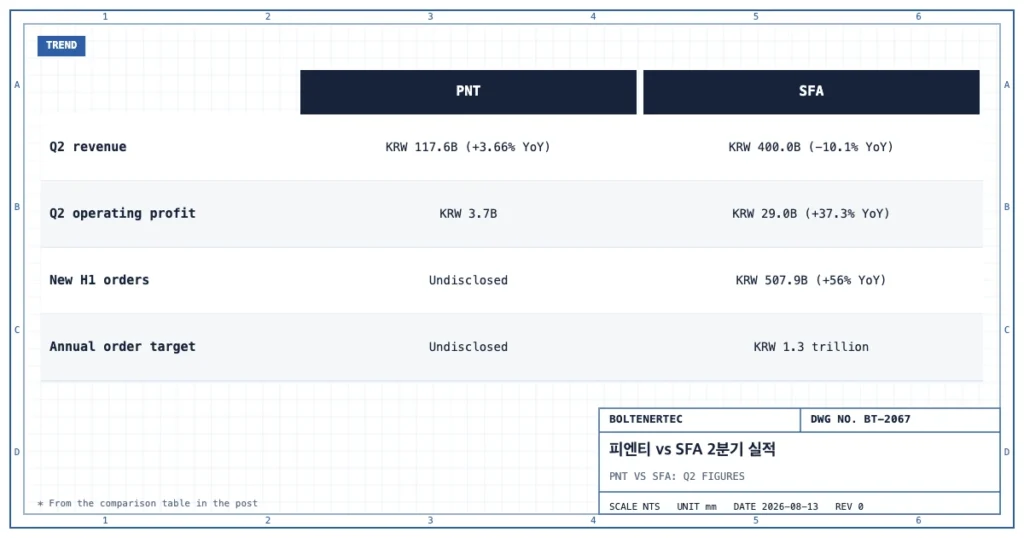
Two Korean battery R2R equipment makers released Q2 results. PNT posted consolidated revenue of KRW 117.6 billion (+3.66% YoY), operating profit of KRW 3.7 billion, and net profit of KRW 7.0 billion. SFA posted revenue of KRW 400.0 billion (–10.1% YoY) and operating profit of KRW 29.0 billion (+37.3% YoY).
| Category | PNT | SFA |
|---|---|---|
| Q2 revenue | KRW 117.6 billion (+3.66% YoY) | KRW 400.0 billion (–10.1% YoY) |
| Q2 operating profit | KRW 3.7 billion | KRW 29.0 billion (+37.3% YoY) |
| New H1 orders | (undisclosed) | KRW 507.9 billion (+56% YoY) |
| Annual order target | (undisclosed) | KRW 1.3 trillion |
| Earnings driver | Delivery-schedule delays at equipment customers, fixed-cost burden from new projects | Diversification across semiconductor, fuel-cell, dry-coating, and other downstream industries |
According to Edaily, PNT’s first-half cumulative results were revenue of KRW 219.0 billion, operating profit of KRW 12.5 billion, and net income of KRW 27.1 billion. The company attributed the weak results to three factors: (1) global geopolitical uncertainty and adjustment in the battery industry’s investment cycle, (2) increased bad-debt expense from delivery delays at some customers, and (3) fixed-cost burden including depreciation during the ramp-up phase of new businesses (source: Edaily). PNT said its Chinese subsidiary, Shaanxi Advanced Materials Technology Co., entered a stage of full-scale revenue generation, posting roughly KRW 20 billion in revenue in Q2 (same source).
The gap between PNT’s revenue growth and its relatively small operating-profit scale stems from delivery-schedule delays. For an R2R line integrator, a delivery delay at the customer means the acceptance (FAT/SAT) schedule and the on-site installation schedule slip together. When a customer line’s startup timing is pushed back, the order timing for downstream process equipment (slitters, winders) shifts in a chain reaction.
SFA’s operating profit rose even as revenue declined. A significant portion of its new H1 orders of KRW 507.9 billion came from outside the battery sector — semiconductor, fuel-cell, dry-coating, and other downstream industries. Diversifying its portfolio to reduce dependence on a single industry cycle acted as an earnings buffer.
That delivery delays led not only to deferred revenue recognition but also to increased bad-debt expense shows that, given the equipment industry’s practice of treating installation/commissioning (SAT) completion as the key milestone for revenue recognition, delivery delays feed directly into the financial statements (estimated; basis: the industry convention that R2R equipment makers commonly recognize revenue at installation-acceptance completion). The fact that depreciation for the new businesses (LFP, copper foil, cathode materials) is already being booked as a fixed cost suggests that capital investment in those lines is already close to completion (estimated).
Shop-notes: A new materials-business line (copper foil, cathode material) uses different equipment standards from an existing R2R electrode-assembly line, so operating multiple business lines within the same plant requires separately designing utility (power, cooling water) capacity allocation and clean-room class zoning. Between expanding the existing building and constructing a new one, expanding the existing building is more favorable for reducing upfront investment if utility capacity has margin, but building a new one may be the more reasonable choice for long-term maintenance efficiency once capacity is exceeded (estimated).
One-line summary: PNT’s revenue grew but delivery delays ate into its margin, while SFA’s downstream-industry diversification protected its margin.
According to Edaily, PNT’s order backlog at the end of Q2 increased from the prior quarter, with demand for high-performance electronic components (MLCC, PCB) driven by AI-industry growth emerging as a new order driver (source: Edaily). The company said it expects its LFP battery, copper-foil, and cathode-material businesses to contribute more to earnings starting in the second half (same source).
Design Reflection Checklist
- Identify the cause (FAT/SAT stage) of the delivery delay at the customer generating the bad-debt expense
- Pre-review utility capacity allocation plans for the new copper-foil/cathode-material lines
- Monitor how expanding AI-industry-driven MLCC/PCB equipment demand affects R2R equipment order intake