China’s 2% consumption tax on lithium-ion batteries took effect on September 1, 2026. This ends an 11-year tax exemption.
Key News Facts Summary
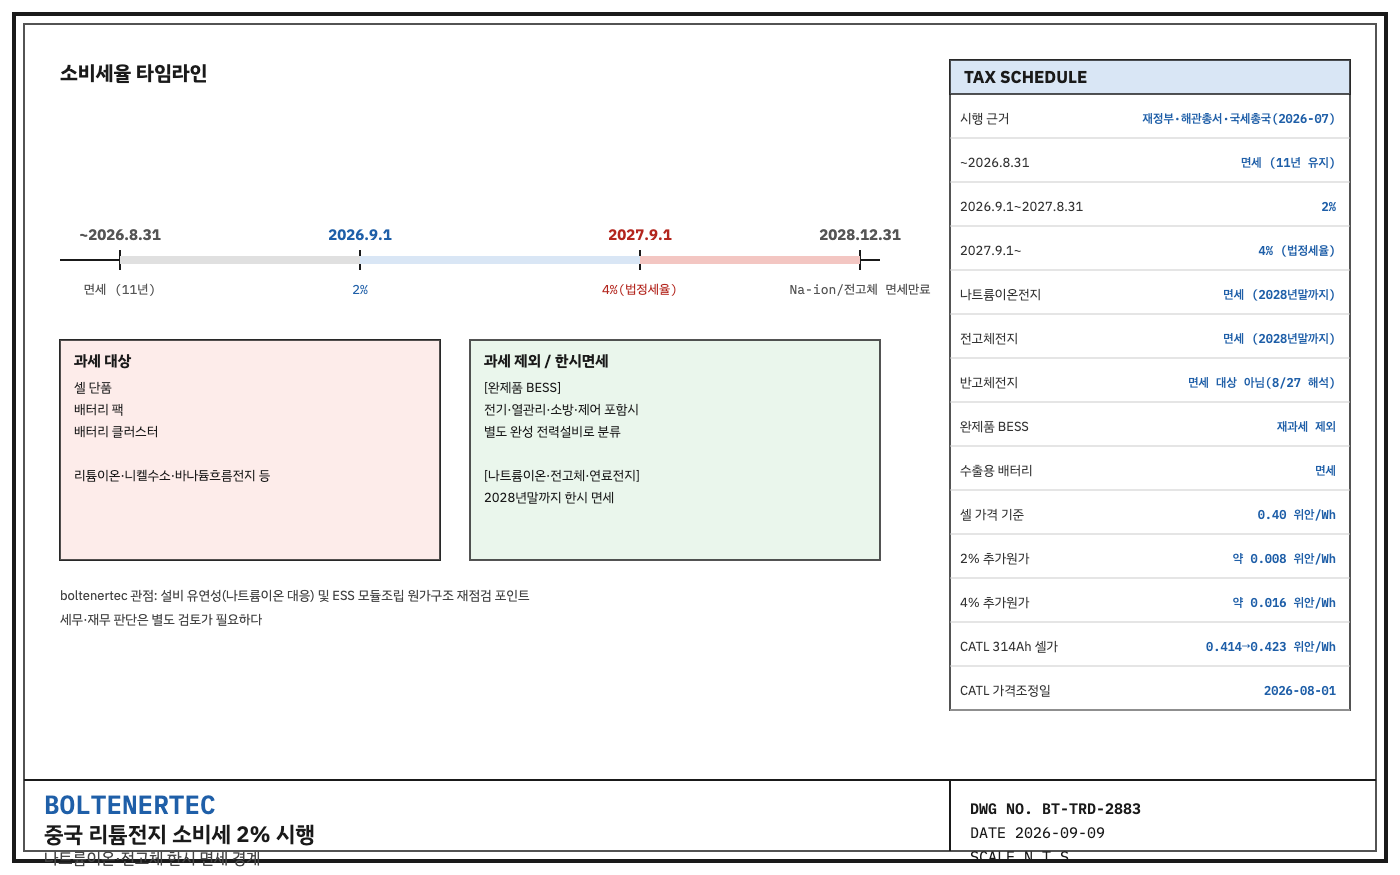
Under a policy jointly announced in July 2026 by China’s Ministry of Finance, General Administration of Customs, and State Taxation Administration, a 2% consumption tax on lithium-ion batteries, primary lithium batteries, nickel-metal-hydride batteries, mercury-free primary batteries, and vanadium redox flow batteries takes effect from September 1, 2026. The rate rises to 4% (the statutory rate) from September 1, 2027 (source: pv magazine Global, September 1, 2026, citing ESS News).
Sodium-ion batteries, all-solid-state batteries, and fuel cells remain temporarily exempt through the end of 2028. On August 27, the State Taxation Administration clarified in a separate interpretation that semi-solid-state batteries do not qualify as “all-solid-state batteries” under this exemption.
The taxable boundary has also been set. Cells, packs, and battery clusters are taxable, but complete BESS products — including electrical equipment, thermal management, fire safety, and control systems — are classified as separate finished power equipment and are not re-taxed. Huatai Securities estimated that, based on a storage-cell price of RMB 0.40/Wh, the 2% rate adds about RMB 0.008/Wh and the 4% rate about RMB 0.016/Wh in cost. CATL raised its 314Ah storage cell online marketplace price from RMB 0.414/Wh to RMB 0.423/Wh on August 1 (reported as an adjustment reflecting supply-demand factors in addition to the tax change). Batteries for export are exempt from the consumption tax.
Impact Analysis from a Mechanical Design Perspective
The tax rate itself falls within finance and tax territory, outside boltenertec’s design scope, and specific profit-and-loss judgments require separate review. From an equipment design perspective, however, two points are worth noting.
First, the temporary tax preference for sodium-ion and all-solid-state batteries creates an incentive for Chinese cell makers to move up their investment timing for the corresponding production lines. For domestic mixer, coater, and stacking equipment makers, this may increase demand for equipment flexibility designs that accommodate sodium-ion-specific slurry properties (differences in viscosity and solids content) and expanded use of aluminum current collectors.
Second, the taxable boundary drawn between cells/packs/clusters and finished BESS products is a cost-structure reexamination point for companies supplying ESS module-assembly equipment to China or modularizing Chinese-made cells domestically. However, control and electrical-design details are mentioned only as boltenertec’s boundary conditions, and specific cost impacts have not been confirmed.
Spec Comparison Table
| Category | Before Sept 1, 2026 | Sept 1, 2026 – Aug 31, 2027 | After Sept 1, 2027 |
|---|---|---|---|
| Lithium-ion, NiMH batteries, etc. | Exempt (11 years) | 2% | 4% (statutory rate) |
| Sodium-ion, all-solid-state batteries, fuel cells | Exempt | Exempt (through end of 2028) | Exempt (through end of 2028) |
| Finished BESS products (incl. electrical, thermal management, fire safety) | Not applicable | Excluded from re-taxation | Excluded from re-taxation |
| Batteries for export | Exempt | Exempt | Exempt |
One-line summary: The implementation of China’s 2% lithium battery consumption tax grants a temporary tax advantage to sodium-ion and all-solid-state batteries, which may act as an indirect variable accelerating investment timing for the corresponding equipment lines.